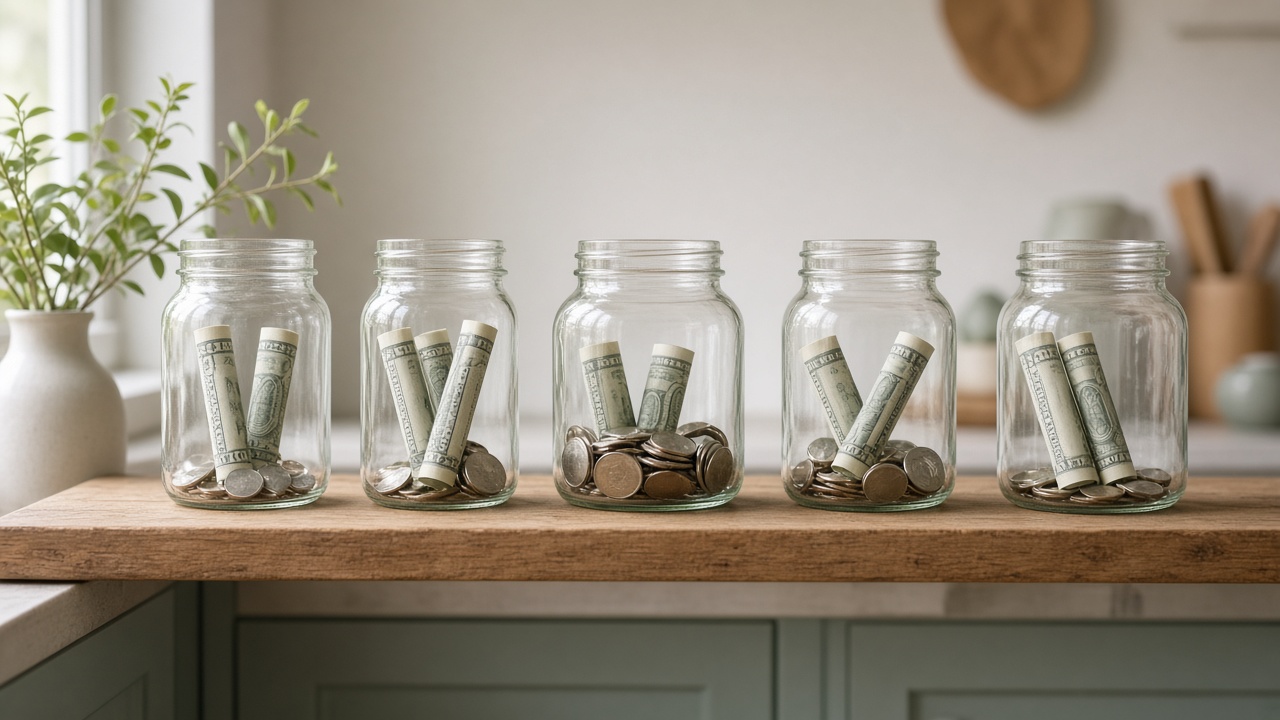
Every December I used to feel ambushed. Gifts, travel, a holiday dinner or two, and suddenly the card balance I’d been chipping away at all year was right back where it started. The strange part is that December wasn’t a surprise. It comes every single year, on schedule.
That’s the gap a sinking fund fills. It’s not a new account type or a clever app. It’s just setting aside a little money each month for a cost you already know is coming, so when it arrives it’s already paid for.
Emergencies vs. things you can see coming
If you’ve read how to build your first $1,000 emergency fund, you know the rule: an emergency is unexpected, necessary, and urgent. A burst pipe counts. Car registration doesn’t, because it shows up on the same month every year.
When predictable costs don’t have their own home, they quietly raid the emergency fund or land on a credit card. Sinking funds keep those two jobs separate. Your emergency fund stays for real surprises, and the known stuff gets its own small bucket.
The simple math
Take the yearly cost, divide it by the number of months until it’s due, and set that amount aside each month. That’s the whole formula.
- Holidays and gifts: $600 a year, due in 10 months = $60 a month
- Car registration and maintenance: $480 a year = $40 a month
- Annual insurance or subscription renewals: $360 a year = $30 a month
- Back-to-school or kids’ activities: $300 a year = $25 a month
Seeing $600 turn into $60 is a little bit of relief all by itself. The cost didn’t change. It just stopped arriving all at once.
Start with your three most annoying bills
You don’t need a dozen funds. Look back at your last twelve months of bank or card statements and find the three expenses that hurt most because they showed up “out of nowhere.” For most people that’s holidays, car costs, and some kind of annual bill. Start there.
Where to keep the money
Keep it simple. A few options, from simplest to most organized:
- One separate savings account for all your sinking funds, with a short note or spreadsheet tracking how much belongs to each one
- A bank that lets you create named “buckets” or sub-accounts inside one savings account
- Cash envelopes, if you like something you can hold (just keep them somewhere safe)
Whatever you choose, keep it separate from your emergency fund. Mixing them is how “I’ll just borrow from the holiday money” becomes a habit.
Automate it, then forget it
Like the emergency fund, this works best when it happens without you. Set one automatic transfer for the total of your monthly sinking fund amounts, the day after payday. If your three funds add up to $125 a month, that’s one $125 transfer, split on paper.
If $125 feels like too much right now, shrink it. Fund the soonest bill first and add the others later. A small fund that exists beats a perfect plan that doesn’t.
What about paying off debt?
If you’re working through the debt snowball, sinking funds can feel like a detour. They’re actually protection for it. Every time a predictable bill lands on a credit card, your snowball gets pushed backward. A modest sinking fund for your biggest known costs keeps your payoff plan moving forward. You can keep your balances on the free Debt Snowball Tracker while these small buckets fill up in the background.
Your one step for this week
Pick one upcoming cost, holidays are a good one right now, and work out the monthly amount. Then set up the transfer. That single bucket is enough to feel the difference the next time that bill comes around.
If you like having everything on paper, The Calm Money Planner includes a sinking funds tracker with monthly check-offs, alongside the emergency fund and debt pages.
Further reading
Disclosure: The book link below is an affiliate link. If you buy through it, I may earn a commission at no extra cost to you. See the Affiliate Disclosure.
If you like the idea of money that runs itself, I Will Teach You to Be Rich by Ramit Sethi has a practical, guilt-free take on automating savings goals like these. And for why small, repeated moves matter so much, read Tiny Daily Habits Build Wealth.
One small next step
If you’re paying off debt, the free Debt Snowball Tracker gives you one simple page to watch your balances shrink. If you’d like the whole system on paper, The Calm Money Planner ($12) adds an emergency fund tracker, sinking funds, a weekly check-in and a monthly budget. New here? Start here.
Leave a Reply